

A federal tax lien often feels like an immovable barrier to your financial future, yet it's frequently a challenge that can be resolved with a methodical and informed approach. You may find yourself concerned about a declining credit score or the inability to refinance your home, especially when the official paperwork feels intentionally complex. It's a stressful position to be in, and your desire for a clear, quiet resolution is entirely valid. This guide provides a strategic look at IRS tax lien removal, offering the professional clarity you need to regain your financial standing in 2026.
We'll examine the specific legal pathways available, including the important distinctions between a lien release and a full withdrawal. You'll also learn how transcript analysis serves as a foundational step in understanding exactly what the IRS sees on your record. By following a structured plan, you can protect your property equity and stop the escalation of collection efforts with confidence.
Key Takeaways
- Learn the fundamental differences between a lien release and a withdrawal to ensure you're choosing the best option for your long-term credit health.
- Discover how specific strategies like property discharge and subordination can help you sell or refinance assets even when a federal tax lien is in place.
- Understand how professional IRS tax lien removal services, led by an Enrolled Agent, utilize transcript analysis to identify errors and build a clear resolution path.
- Find out how to stop the progression of IRS collection activities and protect your property equity through methodical, legal pathways.
Understanding IRS Tax Lien Removal: Release vs. Withdrawal
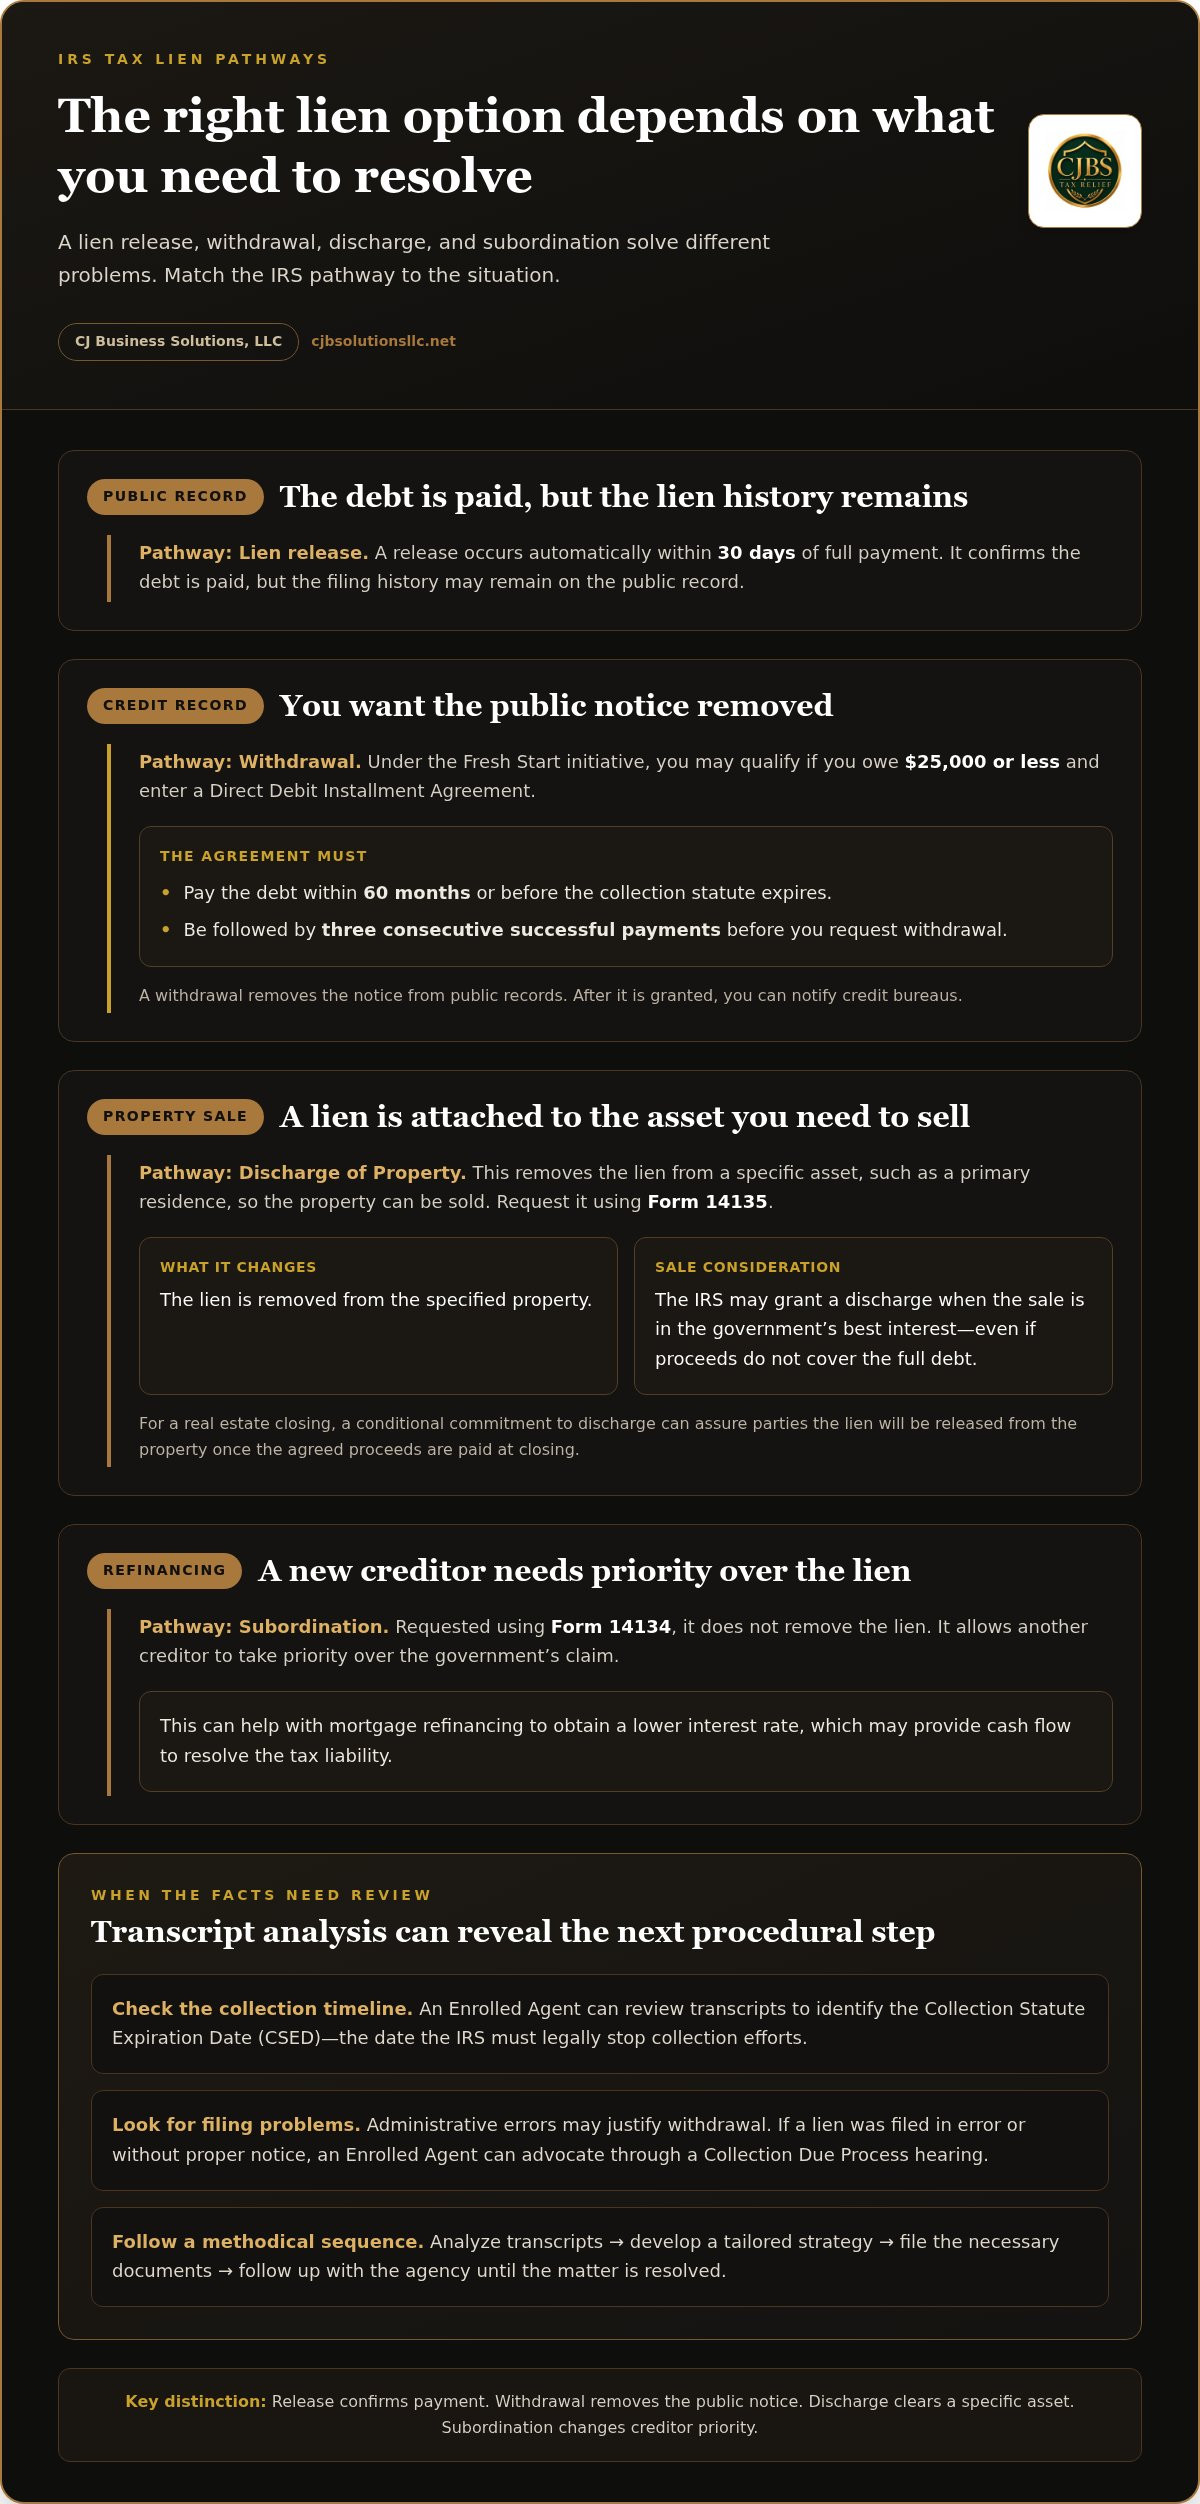
A federal tax lien represents the government's legal claim against your property, securing a debt that remains unpaid. For a foundational perspective, Understanding Tax Liens provides clarity on how these claims affect your assets. While most taxpayers focus on a "Lien Release," which occurs automatically within 30 days of full payment, it's often not the most advantageous path for your financial reputation. A release simply notes that the debt is paid, but the history of the lien remains on the public record.
A more strategic approach involves seeking an IRS tax lien removal through a process called withdrawal. Under the Fresh Start initiative, you may qualify for this if you owe $25,000 or less and enter a Direct Debit Installment Agreement. This agreement must be structured to pay off the debt within 60 months or before the collection statute expires. Once you complete three consecutive successful payments, you can request that the public notice be rescinded entirely. This option is particularly helpful for those who have the means to pay down their balance to meet the threshold.
Why Withdrawal is the Superior Goal for Your Credit
While a released lien indicates the debt is satisfied, the record of the filing may persist on public reports for years, potentially hindering your ability to secure favorable interest rates. In contrast, a withdrawal is the IRS effectively saying the lien notice should never have been filed or is no longer necessary. This distinction is vital because a withdrawal allows for the complete removal of the notice from public records. Once the IRS grants this request, you can proactively notify credit bureaus to ensure your creditworthiness is restored as quickly as possible. This methodical approach ensures your history reflects your current financial stability rather than past challenges.
Strategic Paths to Removing Liens from Specific Assets
When you need to sell property or secure a new loan, a blanket lien can feel like an impossible hurdle. However, the IRS provides specific mechanisms to handle these situations without requiring immediate full payment. A "Discharge of Property" removes the lien from a specific asset, such as your primary residence, so it can be sold. You'll typically use Form 14135 for this request. Many taxpayers mistakenly believe they can't sell if the proceeds won't cover the entire debt, but the IRS often grants a discharge if the sale represents the government's best interest. This is a practical step toward an eventual IRS tax lien removal.
Another vital tool is "Subordination," requested via Form 14134. This doesn't remove the lien but allows another creditor to take priority over the government's claim. This is particularly useful when refinancing a mortgage to obtain a lower interest rate, which may ultimately provide you with the cash flow needed to resolve your liability. Reviewing IRS options for lien removal can help you identify which path fits your current financial goals.
Navigating Real Estate Transactions with an IRS Lien
Timing is everything during a property sale. To satisfy title companies and ensure a smooth closing, you can seek a conditional commitment to discharge. This document assures all parties that the lien will be released from the property once the agreed-upon proceeds are paid at closing. If you find the paperwork or the negotiation with a Revenue Officer overwhelming, consulting with an Enrolled Agent for tax resolution can provide the steady guidance needed to stay on track. This methodical approach prevents delays and protects your equity while you work toward a permanent IRS tax lien removal.
The Professional Path to Permanent Resolution
Achieving a permanent resolution often requires more than just filling out standard forms; it involves a strategic partnership with a professional who understands the internal mechanics of the agency. An Enrolled Agent (EA) serves as your representative, acting as a steady buffer between you and IRS Revenue Officers. This professional oversight significantly lowers the emotional weight of the process, ensuring that every communication is handled with technical precision and calm authority. While the official documentation on Understanding a Federal Tax Lien outlines the basics, an EA looks deeper into the nuances of your specific case. If a lien was filed in error or without proper notice, they can advocate for your rights through a Collection Due Process hearing. This isn't just a temporary solution; it's a comprehensive long-term compliance strategy that secures your financial standing for years to come.
How Transcript Analysis Unlocks Removal Opportunities
A key advantage of professional representation is the use of specialized transcript analysis services. By reviewing your official records, an EA can identify the Collection Statute Expiration Date (CSED), which is the precise day the IRS must legally stop its collection efforts. If the statute has expired, an IRS tax lien removal becomes a matter of procedural law rather than complex negotiation. They also look for administrative errors in the filing process that may justify an immediate withdrawal of the notice. The engagement follows a methodical path: a thorough analysis of your transcripts, the development of a tailored strategy, the precise filing of necessary documents, and consistent follow-up with the agency until the matter is resolved. This thorough approach ensures that every possible opportunity for an IRS tax lien removal is explored and secured.
Restoring Your Financial Clarity and Confidence
Resolving a federal tax lien is a methodical process that requires an understanding of both the law and the specific administrative pathways the IRS provides. Whether you're seeking a withdrawal for your credit or a property discharge for a sale, the right strategy makes all the difference. By utilizing specialized transcript decoding and expert representation, you can address the root of the issue rather than just the symptoms. This journey toward stability begins with seeing exactly what the IRS sees on your record.
If you're ready to move forward with a clear plan for IRS tax lien removal, we're here to help. Request a professional transcript analysis from CJ Business Solutions, LLC to start your lien resolution today. With the guidance of a seasoned Enrolled Agent specializing in collection defense, you can find the most direct path to financial freedom. You've taken the first step by educating yourself, and a brighter financial future is well within your reach.
Frequently Asked Questions
How long does it take for the IRS to remove a tax lien after payment?
The IRS typically releases a federal tax lien within 30 days of the debt being paid in full. This release is the standard administrative response to a zero balance. If you require an IRS tax lien removal through a formal withdrawal, you must submit a separate request. A withdrawal is often more beneficial for your credit history because it rescinds the public notice entirely.
Can I sell my house if I have an IRS tax lien?
You can sell your home even with an active lien by applying for a Certificate of Discharge. This process removes the lien from the specific property being sold so the title can transfer to the buyer. You'll generally use Form 14135 to request this. The IRS often approves a discharge if the sale proceeds help settle your tax liability or protect the government's interest.
What is the difference between a tax lien and a tax levy?
A tax lien is a legal claim the government makes against your property to secure a debt; a levy is the actual seizure of assets to satisfy that debt. A lien acts as a security interest that protects the government's priority among creditors. In contrast, a levy is an aggressive action where the IRS takes funds from bank accounts or garnishes wages to settle the balance.
Does an IRS tax lien ever expire?
A federal tax lien generally expires when the underlying tax debt is no longer legally collectible. This occurs at the Collection Statute Expiration Date, which is usually ten years after the assessment. Utilizing specialized transcript analysis services can help you identify these specific dates. Once the statute expires, the IRS tax lien removal is essentially automatic, though you should confirm the public record is updated.

Article by
Crystal R. Johnson, MBA EA
Crystal Johnson founded CJ Business Solutions to give individuals and small-business owners something often missing from the tax and accounting process: clear explanations, practical solutions, and trusted support.
With more than 27 years of accounting and financial experience, Crystal helps clients understand complicated tax matters, restore compliance, respond to IRS concerns, and make stronger business decisions. As an Enrolled Agent, she is federally authorized to represent taxpayers before the Internal Revenue Service.


